

Falling property rates and record reinsurance capital are giving commercial insurance buyers more leverage as companies set their 2027 risk budgets.

As construction backlogs swell, surety underwriting is becoming a second layer of diligence procurement teams can use before committing to a contractor.

Insurers are looking deeper into supplier networks as concentrated sourcing and hidden upstream dependencies reshape business interruption risk.

Power availability and PPA terms are becoming more consequential in transaction and underwriting decisions as electricity constraints affect asset value.

Data center leases can pass utility rate, demand, capacity and transmission costs to tenants, creating power exposure enterprise buyers may overlook.

Battery failure rates fell 98% from 2018 to 2024 as developers moved safety testing, fire planning, and public engagement earlier in development.

Moody's July update puts hyperscaler lease commitments at $1.2 trillion, up from $969 billion in February, with most growth still off balance sheets.

A survey of 400-plus data center executives and widening bond spreads point the same direction: construction problems are showing up in financing costs.

More than 12,000 claimants have filed for payment through SCE's Eaton Fire settlement fund, even as Edison discloses 2,000 lawsuits and $1.3 billion in losses.

Data center, power and infrastructure megaprojects are concentrating risk across the same contractor and surety markets, straining bonding capacity.
Curtailment orders, discharge limits, and insurance exposure are the water liabilities confronting industrial operations already built and operating in stressed basins.
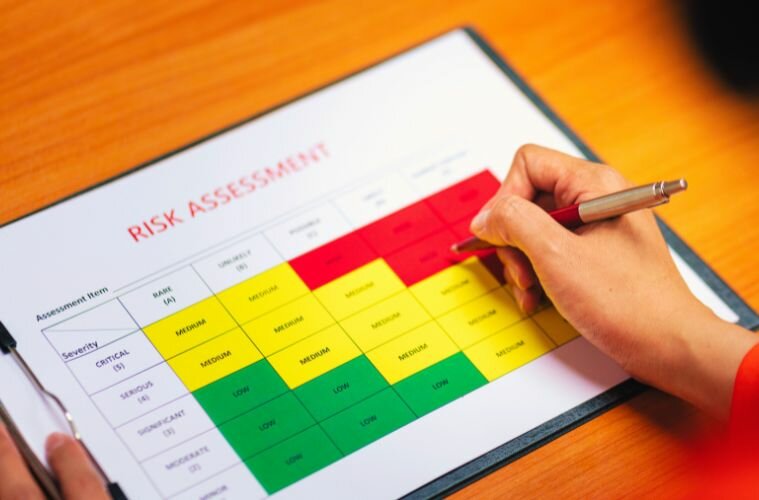
Heat enforcement, grid constraints, supply chain exposure, and AI infrastructure demands altered corporate risk profiles in Q2. Many companies are still operating from outdated assumptions.

Clean energy project finance credit standards shifted in 2025 and 2026. Companies with infrastructure commitments built on older assumptions are running into those changes now.
MSCI's 2026 methodology update is changing ESG scores for 37% of rated issuers. Sustainability and finance leaders need to know what drives the shift before investors ask.

Regulators want data with a documented chain of custody. Assurance providers want controls, not commitments. Most corporate sustainability programs were not built for any of those three things.

UHERO's 2026 Housing Factbook documents declining condo prices, surging insurance premiums, and new FEMA flood map changes arriving in June that will raise carrying costs further.

Why flooding, heat, and drought are degrading facility values and restricting insurance access faster than corporate financial models account for.

Organizations that haven't conducted a systematic PFAS exposure assessment are making that decision by default, and the cost of finding out later is rising.

NGO environmental scorecards used to be a reputation management concern. The way they're being used now — by investors, insurers, and buyers — has changed that calculus entirely.

How much of your portfolio exposure sits in land and environmental risk your current compliance framework was not built to catch?